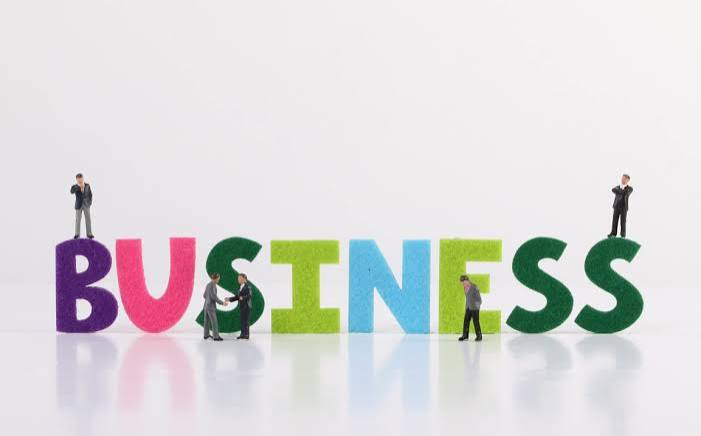
Colorful felt letters spell out the word “BUSINESS,” and tiny figurines in suits stand around them: two on top of the first and last letters, two shaking hands beside an S, and one bending over as if inspecting something near the E. It is a toy-sized scene, and it makes a fair point about the sector that supports most of Bangladesh’s economy: small enterprises.
What the image shows
The photograph shows a row of fuzzy, felt-textured capital letters in purple, pink, dark green, lime, sky blue and olive against a clean white background. Five miniature businessmen figures are placed around them. Two stand on top of the B and the final S, as if surveying the scene. Two meet in a handshake in front of the first S. A fifth bends forward near the E, looking down. Their reflections shimmer on the glossy surface below.
The picture works as a symbol of small-scale commerce: people making deals, inspecting details and keeping watch from the top.
The backbone of the economy
In Bangladesh, the term most often used is CMSME, short for cottage, micro, small and medium enterprises. These range from home-based craftspeople and corner shops to small factories. Nearly 95 percent of businesses in the country fall into the CMSME category. They contribute roughly 30 percent of GDP and account for about 85 percent of industrial employment, and the Ministry of Industries has set a target of raising their share of GDP above 60 percent. Other sources give slightly different figures, with SME Foundation data putting the micro, small and medium sector’s contribution at nearly 32 percent of the economy, so the exact share depends on definitions and data years. The foundation’s chairperson has said nearly 1.18 crore MSME entrepreneurs have yet to realize their full potential because of a lack of funding. shifting away from collateral based lending key to cmsme survival +3
A leading economist described the sector’s role this way: it is one of the main pillars of the economy, and building a stronger sector is essential for sustainable industrialization and quality employment. cpd
The financing squeeze
Money is the recurring obstacle. The latest central bank figures show lending to the sector moving the wrong way. Total outstanding CMSME loans across banks and non-bank financial institutions shrank by 5.14 percent in the first quarter of 2026, falling from Tk314,273 crore in December 2025 to Tk298,089 crore in March 2026. The wider credit picture is weak too: private-sector credit growth stood at only 4.98 percent as of May 31, 2026. dhakatribunethefinancialexpress
Entrepreneurs and bankers point to several causes:
- Collateral demands. One banker argues that a shift from collateral-based to cash-flow-based lending is the key change needed for sustainable CMSME growth. thefinancialexpress
- Paperwork and information gaps. Experts at a roundtable cited cumbersome paperwork, collateral requirements, information gaps and implementation challenges despite supportive central bank policies. tbsnews
- Cautious banks. Banks have been scaling back disbursements amid rising defaults and persistent inflation, while shrinking consumer demand has left some entrepreneurs unable to sustain or expand operations. apparelresources
- High costs of small loans. The high administrative and transaction costs of lending small amounts and monitoring them do not make SME financing very profitable for lenders. observerbd
What the government is doing
Policymakers have announced support. The proposed budget plans to channel Tk2,000 crore in SME loans through the SME Foundation, IDCOL and BIFFL, while Bangladesh Bank will provide more than Tk7,000 crore in financing support, including Tk5,000 crore under its refinancing scheme for the CMSME sector. Economists welcome the attention but say it is not enough by itself. The same economist argued that the sector requires much greater support than this, and the government alone cannot meet all financing needs, and that bureaucratic hurdles remain one of the biggest obstacles for entrepreneurs. cpdcpd
Women entrepreneurs left behind
The gap is widest for women. Female entrepreneurs held only 7.28 percent of total outstanding CMSME loans as of March 31, 2026, despite dedicated refinance schemes and priority guidelines. Bankers and grassroots entrepreneurs point to social land-ownership patterns that leave few women with property titles to offer as collateral, and the report highlights scaling up central bank credit risk-sharing guarantees for unsecured loans. dhakatribunedhakatribune
Beyond manufacturing
The picture of small business is also changing. The SME sector is no longer limited to manufacturing, and many small and medium firms are trying to expand into international markets. Online sellers, freelancers, food producers, agro-processors and service providers all belong to the broader group, which is why economists say that one policy cannot serve every enterprise. cpd
What would help
Based on the views quoted in recent coverage, the main ideas on the table include:
- Cash-flow-based and collateral-free lending, supported by digital data
- Simpler procedures and better capacity within banks
- Stronger monitoring so that funds reach the intended businesses
- Alternative financing sources beyond banks and non-bank lenders
- Targeted support for women entrepreneurs, including credit guarantees
- Improved financial literacy among small business owners
Tips for small business owners
- Keep clear, regular records of sales, costs and cash flow, since lenders increasingly look at them.
- Separate personal and business finances.
- Learn about refinancing and guarantee schemes offered through banks and the SME Foundation.
- Compare loan terms, including fees and interest, before borrowing.
- Be wary of informal lenders and “too good to be true” offers.
The takeaway
The little figurines in the photograph shake hands, look down at details and keep watch from above, which is more or less what running a small business involves. Their size is deceptive: collectively, such firms employ most of the country’s industrial workforce. Whether Bangladesh’s economy regains momentum may depend in large part on whether these small enterprises can get the credit, support and confidence they need.
Copyright & Disclaimer
© 2026 Frontara News. All rights reserved. This article is original content written for frontaranews.com. No part may be reproduced, copied or redistributed without prior written permission, except for brief quotations with proper credit and a link back to the original article.